Good debt v Bad debt
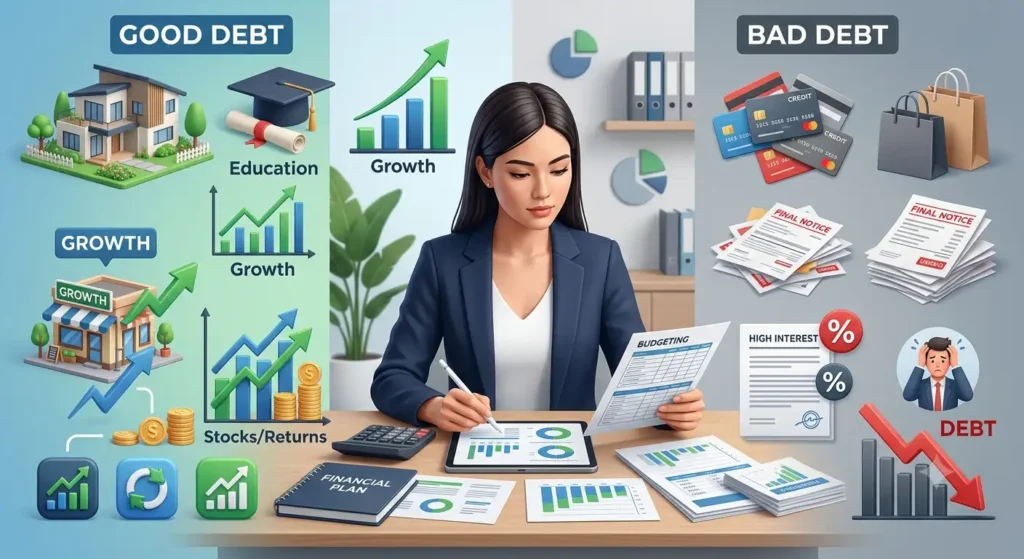
Good debt v Bad debt-Explained Debt is often viewed negatively because borrowing money without proper planning can create financial stress. However, not all debt is harmful. The impact of borrowing depends on how the money is used, the repayment plan, and the long-term value it creates. Understanding the difference between good debt v bad debt helps individuals and businesses make better financial decisions. In this blog, Team Taxperts, a professional tax consultant in Kerala, breaks down the key differences between good debt and bad debt. This understanding can help individuals and businesses make informed choices about loans, investments, and repayments while maintaining financial stability. Proper financial planning, along with expert guidance, can help manage financial obligations, understand tax-related impacts, and build a stronger financial future. Good debt Good debt refers to borrowing money that has the potential to create long-term financial benefits. This type of debt is usually taken to invest in assets, improve earning capacity, or support future growth. The key factor that makes debt “good” is whether the borrowed money contributes to building value over time. Good debt is generally associated with planned borrowing, reasonable interest rates, and a clear repayment strategy. When managed properly, it can help individuals achieve important financial goals that may not be possible through savings alone. For example, taking a loan to purchase a home, pursue higher education, or expand a profitable business can provide future financial advantages. Although repayment obligations exist, the benefits gained from these investments may outweigh the cost of borrowing. Examples of Good Debt Some common examples of good debt include: 1. Home loans A home loan is often considered good debt because it helps individuals purchase a long-term asset. Over time, the property may increase in value, creating wealth for the borrower. Additionally, home ownership can provide financial security compared to continuously paying rent. 2. Education loans Education loans can be considered good debt when they help individuals gain skills, qualifications, or professional training that improve their career opportunities and earning potential. 3. Business loans Loans used to start or expand a business can be beneficial if the borrowed funds generate revenue and support business growth. Proper financial planning and repayment management are important to ensure the loan contributes positively to the business. 4. Loans for income-generating assets Borrowing money to purchase assets that generate income, such as equipment for a business or tools required for professional work, can be considered good debt when the expected returns justify the borrowing cost. Bad debt Bad debt refers to borrowing money for expenses that do not create long-term financial value or improve earning potential. This type of debt can become a financial burden, especially when it involves high interest rates, unnecessary spending, or difficulty in repayment. Bad debt usually arises when individuals borrow beyond their means or use loans to finance lifestyle expenses without considering their financial capacity. Over time, accumulated interest and repayment obligations can negatively affect savings and financial security. While occasional borrowing may not always cause problems, consistently relying on bad debt can lead to cash flow issues and increased financial pressure. Examples of Bad debt Some common examples of bad debt include: 1. High-interest credit card debt Credit cards can become a source of bad debt when balances are not paid on time. High interest rates can quickly increase the outstanding amount, making repayment more difficult. 2. Personal loans for unnecessary expenses Taking loans for luxury purchases, vacations, or non-essential spending without a proper repayment plan may create financial stress, as these expenses usually do not provide future financial returns. 3. Borrowing for depreciating assets Loans taken to purchase non-essential depreciating assets, such as expensive gadgets or luxury vehicles beyond one’s financial capacity, may become bad debt if the repayment burden exceeds the financial benefit received. 4. Loans used to repay other debts Repeatedly borrowing money to clear existing loans can create a cycle of debt. Without addressing the underlying financial issues, this approach can increase financial difficulties. How can one avoid bad debt? Avoiding bad debt requires careful financial planning and responsible borrowing habits. Some effective ways to prevent unnecessary debt include: Create a realistic budget: Track income, expenses, and savings to understand how much borrowing you can comfortably manage. Borrow only when necessary: Before taking a loan, evaluate whether the purchase or investment will provide long-term value. Understand loan terms: Check interest rates, repayment periods, processing fees, and other charges before accepting any loan. Maintain an emergency fund: Having savings for unexpected expenses can reduce the need to rely on high-interest loans. Pay credit card bills on time: Clearing credit card balances regularly helps avoid accumulating costly interest charges. Prioritise repayment: Focus on clearing high-interest debts first to reduce financial pressure. Seek professional guidance: Financial experts and tax professionals can help you understand the impact of borrowing decisions and create better financial strategies. Conclusion Understanding good debt v bad debt is important for making responsible financial decisions. Good debt can help build assets, improve income opportunities, and support long-term goals when managed properly. On the other hand, bad debt can reduce financial stability and create unnecessary repayment challenges. The key difference lies in how borrowed money is used and whether it contributes to future financial growth. By planning carefully, borrowing responsibly, and seeking expert advice when required, individuals and businesses can use debt as a financial tool rather than allowing it to become a burden.
Types of Equity Shares?
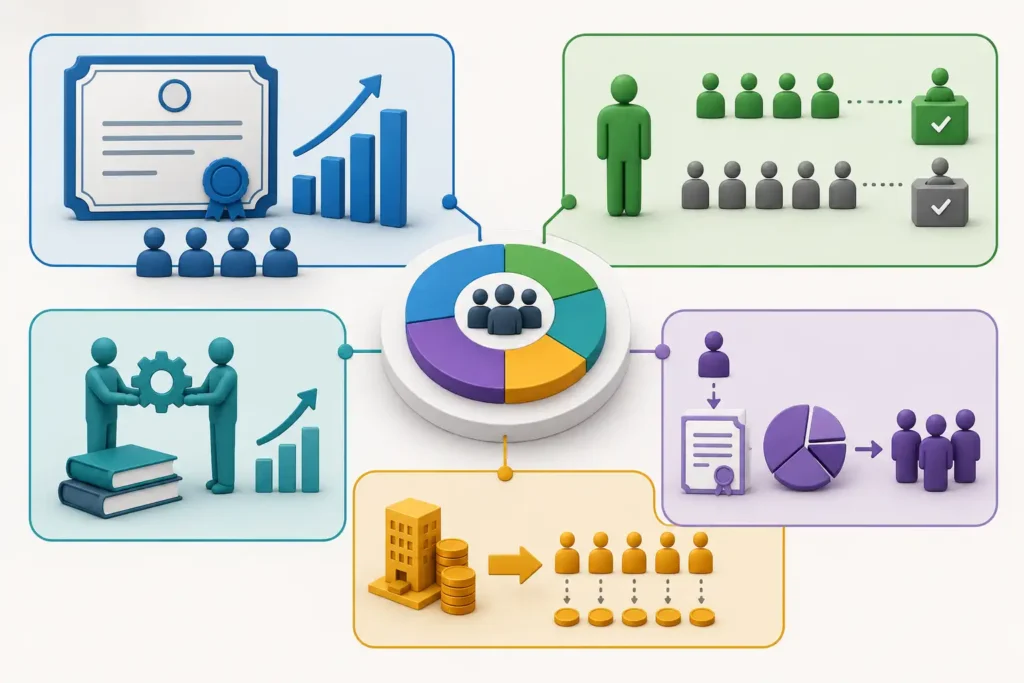
The Ultimate Guide to Types of Equity Shares: Maximizing Capital & Compliance Introduction to Share Capital: What Lies Beyond the Basics? Equity shares represent the foundation of corporate ownership, allowing individuals and institutions to become part-owners of a company. When a business raises funds through equity, investors receive ownership rights in exchange for their capital contribution. Understanding the Types of Equity Shares is essential for entrepreneurs, investors, and companies because each category carries different rights, control mechanisms, and financial implications. Before issuing shares, companies must understand the structure of their share capital. Authorized capital refers to the maximum amount of share capital a company is permitted to issue as stated in its constitutional documents. Issued share capital represents the portion of authorized capital that has actually been offered to shareholders. Through equity ownership, investors gain fractional ownership in a company, making equity shares a crucial instrument in modern corporate finance. Choosing the right type of equity structure helps companies raise funds efficiently while maintaining compliance with corporate regulations. Different equity classifications allow businesses to balance investor expectations, founder control, employee incentives, and long-term growth objectives. For businesses in Kerala, professional guidance is essential when structuring ownership and managing tax obligations. Team Taxperts helps companies with corporate structuring, taxation, and regulatory compliance, making the firm a reliable partner for businesses seeking expert assistance from a tax consultant in Kochi kerala. What Are the Main Types of Equity Shares? (An Overview) Companies issue different types of equity shares based on ownership rights, voting power, and financial benefits. While all equity shareholders hold a stake in the company, the rights attached to each category may differ depending on the company’s objectives and regulatory requirements. The primary Types of Equity Shares include: Ordinary Shares: These are the most common equity shares that provide shareholders with ownership rights and voting power. Investors may receive dividends based on the company’s performance and hold a residual claim over company assets after all liabilities are settled. Differential Voting Rights (DVRs): These shares provide different voting rights compared to ordinary shares. Companies often use DVRs to allow founders and key stakeholders to maintain control while raising external capital. Sweat Equity Shares: These shares are issued to employees or directors in recognition of their contribution, expertise, intellectual property, or value additions to the company. The classification of equity shares allows companies to design a capital structure that supports growth while aligning shareholder interests. Ordinary shares generally suit regular investors, DVRs are useful for companies seeking to protect management control, and sweat equity is beneficial for attracting and retaining key talent. Ordinary Shares: The Standard Types of Equity Shares Ordinary shares are the most widely issued class of equity shares and are commonly traded by investors through stock exchanges. These shares represent direct ownership in a company and provide shareholders with standard ownership benefits. One of the primary features of ordinary shares is voting rights, allowing shareholders to participate in important corporate decisions, including the appointment of directors and approval of major business actions. Ordinary shareholders generally hold shares on a pari-passu (equal footing) basis, meaning all shareholders of the same class enjoy equal rights regarding dividends, voting, and distribution of assets. Unlike debt instruments, equity shares do not create mandatory repayment obligations for the company. Businesses issue ordinary shares to secure permanent capital without increasing their debt burden. This allows companies to invest in expansion, innovation, and long-term growth without the pressure of fixed interest payments. In the event of company liquidation or winding up, ordinary shareholders receive their share of remaining assets only after creditors, preference shareholders, and other priority claims have been settled. Therefore, they are considered residual claimants because their returns depend on the company’s overall financial performance. For everyday investors, ordinary shares provide an opportunity to participate in business growth and benefit from capital appreciation and dividends. However, the returns are directly linked to market performance and company profitability. Differential Voting Rights (DVR): Special Types of Equity Shares Differential Voting Rights (DVR) shares are a specialized category of equity shares designed to provide companies with greater flexibility in managing ownership and control. These shares allow companies to raise capital from investors while enabling founders or existing promoters to retain decision-making authority. DVR shares typically provide different voting rights compared to ordinary shares. For example, a company may issue DVR shares where each share carries only one-tenth of the voting rights of a regular equity share. In return for reduced voting rights, DVR shareholders may receive additional benefits such as a slightly higher dividend payout or dividend premium. This structure is particularly useful for startups and growing companies that require multiple rounds of funding but want to prevent excessive dilution of founder control. By issuing DVR shares, businesses can attract passive investors who are primarily interested in financial returns rather than participating in management decisions. DVR shares also help companies protect themselves against situations such as hostile takeovers, where external parties attempt to acquire control by purchasing a significant number of voting shares. By maintaining stronger voting power among founders or strategic shareholders, companies can preserve their long-term vision. However, companies must carefully design DVR structures because differences in voting power can affect investor confidence and corporate governance. Proper legal and tax guidance is necessary to ensure compliance with applicable regulations. Sweat Equity: Employee-Focused Types of Equity Shares Sweat equity shares are issued by companies to employees or directors as recognition for their contribution, expertise, or efforts that create value for the organization. Instead of providing only cash-based compensation, companies can use equity ownership as a form of non-cash consideration for individuals who contribute significantly to business growth. These shares are commonly issued to acknowledge contributions involving technical expertise, innovation, strategic development, or Intellectual Property Rights (IPR). By offering ownership opportunities, companies can motivate key employees and align their interests with the long-term success of the business. The value of sweat equity may arise from an employee’s specialised knowledge, skills, or value additions that contribute significantly
What is Equity in Stock Market?
Equity in Stock Market Many people who are interested in the stock market often come across terms that create confusion while making investment decisions. One such important concept is equity. Investors often have doubts about what equity means, how equity shares work, and why they are important in stock market investments. In this blog, Team Taxperts, the best tax consultants in kerala, break down these concepts and provide clear guidance on important financial and tax-related matters to help investors make informed decisions. Equity in the stock market refers to the ownership interest that investors hold in a company by purchasing its shares. When an investor buys equity shares, they become a shareholder and gain a partial ownership stake in that company. The value of this ownership depends on the number of shares held and the overall performance of the business.Companies issue equity shares to raise capital for expansion, operations, and future growth. Investors purchase these shares with the expectation of earning returns through an increase in share value and, in some cases, dividends. Having a clear understanding of equity helps investors analyze companies, evaluate opportunities, and make informed financial decisions. How Equity Works? Equity works by representing ownership in a company. When a company issues shares, investors provide capital in exchange for ownership rights. The shareholders may benefit from an increase in the company’s share price and may receive dividends if the company distributes profits.For example, if a company issues shares to the public and an investor purchases those shares, the investor becomes a shareholder. As a part-owner, the investor has a residual claim on the company’s assets after all liabilities are settled. The value of equity can change based on several factors, including company performance, market conditions, industry trends, and investor demand. A company with strong financial performance may experience an increase in share value, while poor performance can negatively affect equity prices. Types and Methods of Issuing Equity Shares Equity shares are mainly classified based on the rights and benefits provided to shareholders. The common types include: 1. Ordinary Equity Shares (Common Shares) Ordinary equity shares are the most common type of shares issued by companies. Shareholders usually have voting rights and may earn returns through dividends and capital appreciation based on the company’s performance. 2. Bonus Shares Bonus shares are additional equity shares issued by a company to existing shareholders without any extra cost. They are issued by converting accumulated reserves or retained earnings into share capital. 3. Rights Shares Rights shares are additional equity shares offered by a company to its existing shareholders at a predetermined price before being offered to the general public. This allows existing shareholders to maintain their ownership percentage in the company. 4. Sweat Equity Shares Sweat equity shares are issued by a company to employees or directors in recognition of their contribution, knowledge, skills, or efforts toward the company’s growth. These shares are generally issued at a discount or for consideration other than cash, as permitted under applicable regulations. 5. Employee Stock Option Scheme (ESOP) Shares ESOP shares are equity shares offered to employees through a stock option plan. They provide employees with an opportunity to own shares in the company, usually after meeting specific conditions such as a vesting period. 6. Voting and Non-Voting Equity Shares Some companies issue equity shares with different voting rights. Voting equity shares provide shareholders with voting rights, while non-voting equity shares may offer other benefits but have limited or no voting rights. For detailed information about different types and features of equity shares, check our blog about equity types. Core Characteristics of Equity Shares Equity shares have certain key characteristics that define their role in the stock market and differentiate them from other investment options. The major characteristics include: 1. Ownership in the Company Equity shareholders become partial owners of the company. Their ownership percentage depends on the number of shares they hold compared to the total shares issued. 2. Voting Rights Most equity shareholders have voting rights, allowing them to participate in important company decisions and elect the board of directors. 3. Variable Returns Returns from equity shares are not fixed. Investors may earn profits through capital appreciation and dividends, depending on the company’s performance and market conditions. 4. Higher Risk and Growth Potential Equity shares generally carry higher risk compared to fixed-income investments. However, they also provide the potential for higher long-term returns. 5. Transferability Equity shares of publicly listed companies can generally be bought and sold on stock exchanges, allowing investors to transfer ownership. 6. Residual Claim on Assets In case of company liquidation, equity shareholders have a claim on remaining assets after all liabilities and obligations are settled. It is significant to understand that equity shareholders have the lowest priority in receiving payments. They are paid only after secured creditors, unsecured creditors, and preference shareholders have received their dues. How Tax Consultants Help Stock Market Investors Stock market investments involve various tax considerations, including capital gains tax, reporting requirements, and compliance obligations. Understanding these rules helps investors manage their financial responsibilities effectively. Professional guidance from tax consultants can help investors understand the tax implications related to equity investments, including specific Indian tax concepts such as STCG (Short-Term Capital Gains), which applies to gains from equity investments held for a short period, and LTCG (Long-Term Capital Gains), which applies to gains from equity investments held for a longer period under Section 112A. Understanding these concepts helps investors make informed decisions and manage their tax responsibilities effectively. Calculating short-term and long-term capital gains on equity investments. Understanding applicable tax rules for share transactions. Maintaining proper financial records for tax filing. Planning investments in a tax-efficient manner. Ensuring compliance with income tax regulations. Proper tax planning allows investors to make informed decisions while managing their overall financial goals. Equity in Company Balance Sheets In accounting, equity represents the value that belongs to shareholders after deducting a company’s liabilities from its assets. It is an important section of a company’s balance sheet and
ETF NFO
Demystifying the ETF NFO: The Smart Investor’s Guide to Ground-Floor Index Investing Passive investing has changed the way people accumulate money. As more investors choose reduced costs, better transparency, and long-term market involvement, traditional active fund management is giving way to index-based investment techniques. Exchange-traded funds (ETFs), which provide a cost-effective means of gaining diversified market exposure, have gained popularity as a result of this trend. One of the most interesting ways to enter this market is through an ETF New Fund Offer (NFO), which is the initial launch phase of an Exchange Traded Fund by an Asset Management Company (AMC). During a New Fund Offer, investors can purchase units before the ETF begins trading on the stock exchange, often at its initial Net Asset Value (NAV). While similar in concept to the launch of classic mutual fund schemes, ETF NFOs have distinct characteristics, benefits, and considerations that all investors should be aware of. Whether you’re looking to minimise expense ratios, broaden your portfolio, or gain early exposure to emerging market themes, knowing how ETF NFOs work can assist you in making informed investment choices. In this guide, we’ll break down ETF NFOs, explain how they differ from traditional fund launches, and help you decide if they’re a good fit for your financial goals and investment horizons. What Exactly is an ETF NFO in Mutual Funds? An ETF New Fund Offer (NFO) is the initial phase of a new Exchange Traded Fund, allowing investors to purchase units before the fund is listed and begins trading on a stock exchange. Similar to the launch of other mutual fund products, this initial subscription period is when the fund gathers funds from investors to build its investment portfolio. Once the subscription window has closed and units have been allocated, the ETF is listed on the market, where investors can buy and sell units in the same way that they would stocks. Unlike actively managed mutual fund schemes, an ETF is often designed to passively track the performance of a benchmark, such as a stock market index, commodity, industry sector, or investment theme. Rather than attempting to outperform the market, the ETF seeks to replicate the returns of its underlying asset by holding the same assets in comparable quantities. This method typically leads to lower management costs and increased transparency. During an ETF NFO, units are distributed at a predetermined allotment price, allowing investors to participate from the start. The fund manager is responsible for constructing the portfolio in line with the ETF’s stated objective and guaranteeing that it closely mirrors the performance of the chosen benchmark. Every ETF NFO is introduced in accordance with SEBI guidelines, which are intended to safeguard investors by ensuring uniform disclosure, openness, and regulatory supervision. While most ETF NFOs are open-ended and remain available for trading after listing, some may be structured around particular investment strategies or fixed-income assets, where factors such as the underlying securities’ maturity profile play an important role in determining risk and return characteristics. Understanding these fundamentals allows investors to determine whether an ETF NFO is consistent with their financial objectives, risk tolerance, and long-term investing plan. How Does an ETF NFO Differ from Traditional Mutual Fund NFOs? Although both an ETF New Fund Offer (NFO) and a typical Mutual Fund NFO mark the start of a new investment scheme, they differ dramatically in terms of how investors buy, sell, and hold their units once the fund is established. Understanding these distinctions is critical for selecting the investment vehicle that best suits your objectives and trading style. During the subscription phase, both products enable investors to participate in the fund’s start. However, what happens after the NFO closes is where the difference becomes clear. Feature Traditional Mutual Fund NFO ETF NFO Purchase During NFO Investors subscribe directly through the Asset Management Company (AMC) or authorised distributors. Investors subscribe during the ETF NFO, with units initially created in creation unit sizes. Trading After Launch Units continue to be bought from and redeemed with the AMC. Units are listed on a stock exchange and traded between investors throughout the trading day. Pricing Transactions occur at the end-of-day Net Asset Value (NAV). Prices fluctuate intraday based on market demand and supply, though they generally stay close to the ETF’s NAV. Liquidity Liquidity is provided by the AMC through purchases and redemptions. Liquidity comes from stock market participants, with market makers helping maintain efficient trading. Trading Flexibility Orders are executed only once each business day after the market closes Investors can buy or sell units at any time during market hours, similar to trading shares Demat Account Not mandatory for most mutual fund investments. A Demat and trading account are required to buy and sell ETF units on the exchange Key Structural Benefits of Investing in an ETF NFO An ETF New Fund Offer (NFO) allows investors to take part in a novel approach to investing from the outset. Whether the fund monitors a broad market index, a particular sector, an international benchmark, or a commodity, investing during the NFO provides investors with access to emerging market opportunities from the ground floor. While the launch price does not guarantee higher returns, early participation can be advantageous when the ETF is structured to target long-term growth themes. Low-cost Investment Structure: Since most ETFs passively track a fundamental benchmark instead of relying on active stock selection, they usually have lower expense ratios than actively managed mutual funds. Over longer investment horizons, these lower costs can substantially boost overall returns by lowering the impact of recurring management fees. Portfolio Transparency: ETFs, unlike many actively managed funds, publish their portfolios on a regular basis, allowing investors to easily comprehend the securities they buy. This transparency, combined with low tracking error in well-managed ETFs, helps to ensure that the fund closely matches the performance of its underlying index. Portfolio Diversification: Investors can acquire exposure to hundreds of assets with a single investment, lowering concentration risk without having to buy individual stocks. Beyond
Interval NFOs
Decoding the Interval NFO: Is This Hybrid Mutual Fund Right for Your Portfolio? In today’s unpredictable financial markets, investors are constantly looking for investment opportunities that strike the right balance between liquidity and long-term wealth creation. While traditional mutual fund schemes typically fall into either open-ended or close-ended categories, an Interval New Fund Offer (NFO) introduces a unique alternative by combining the benefits of both structures. Launched by an Asset Management Company (AMC), an Interval NFO allows investors to participate in a fund that opens for transactions only during specified intervals while its Net Asset Value (NAV) is calculated in accordance with regulatory norms. Understanding how Interval NFOs work is essential for aligning investments with your financial goals, tax efficiency, and preferred investment horizons, enabling you to make informed portfolio decisions. What Exactly Is an Interval NFO in Mutual Funds? An Interval NFO is a type of mutual fund that blends the characteristics of open-ended and close-ended schemes. Investors can subscribe to the fund during the initial subscription period, after which the scheme remains closed except for predetermined transaction windows. During these intervals, investors can buy or redeem units based on the applicable NAV.These schemes operate under SEBI guidelines, ensuring transparency and investor protection. Units are initially allotted at the prescribed allotment price, and the fund manager actively manages the portfolio in line with the fund’s objectives and maturity profile. This structure provides investment stability while still offering periodic liquidity to investors. How Does an Interval NFO Operate Differently from Traditional NFOs? Understanding the differences between various mutual fund structures helps investors select the right investment option.Open-ended NFOs: Investors can purchase or redeem units on any business day after the scheme is launched.Close-ended NFOs: Investments remain locked until the maturity date, with limited or no redemption opportunities during the tenure.Interval NFOs: Investors can buy or redeem units only during predefined transaction windows, which may occur quarterly, semi-annually, or annually.This hybrid approach allows fund managers to maintain portfolio stability while offering investors periodic opportunities to access their investments without remaining completely locked in until maturity. Key Structural Benefits of Investing in an Interval NFO Interval NFOs offer several structural advantages for both investors and fund managers.Since investors cannot redeem units daily, fund managers face fewer unexpected redemption pressures. This enables them to focus on executing disciplined long-term investment strategies without frequent portfolio disruptions. For investors, the benefits include: Better portfolio diversification: Interval NFOs allow investors to diversify their investments across different asset classes and securities, helping reduce overall portfolio risk through improved portfolio diversification. Improved investment discipline: Since investors can buy or redeem units only during specific transaction windows, Interval NFOs encourage a disciplined investment approach and discourage emotional decisions based on short-term market fluctuations. Reduced portfolio churning: Limited redemption opportunities reduce unnecessary buying and selling within the fund, resulting in lower portfolio churning and allowing fund managers to follow a stable long-term investment strategy. Greater flexibility than fixed maturity plans: Unlike traditional fixed maturity plans, Interval NFOs offer predefined transaction windows, giving investors periodic opportunities to enter or exit the fund. Exposure to the debt fund space: Depending on the scheme, Interval NFOs may provide exposure to opportunities within the debt fund space while maintaining a structured investment approach. Suitable for lump sum investments: Investors with surplus funds may consider Interval NFOs for lump sum investments, especially when their financial goals and investment horizon align with the fund’s structure. Efficient asset allocation: Interval NFOs can support better asset allocation by helping investors balance different investment categories according to their long-term financial goals and risk tolerance. Risks and Disadvantages of an Interval NFO You Must Know Like every investment product, Interval NFOs also carry certain risks that investors should evaluate carefully. The primary limitation is restricted liquidity. Investors can redeem their investments only during specified transaction windows, making these funds less suitable for individuals who require immediate access to their money. Other considerations include: Limited historical data, making it difficult to assess the fund’s long-term market performance. Potential exit load, depending on the redemption conditions specified by the scheme. Performance fluctuations due to market volatility. Dependence on the quality of the fund manager’s investment decisions. Before investing, carefully read the Scheme Information Document (SID) to understand the investment strategy, associated risks, eligibility conditions, and other important details, and make an informed investment decision. Tax Implications of an Interval NFO: Expert Insights Taxation plays a significant role in determining the overall returns from any investment. The tax treatment of an Interval NFO depends on whether the scheme is classified as equity-oriented or debt-oriented under the applicable provisions of Indian tax laws. Capital appreciation may be subject to capital gains tax, while the applicable tax treatment varies based on factors such as the nature of the scheme, holding period, and prevailing tax regulations. Investors should also ensure proper tax compliance by accurately reporting investment income during income tax return filing. Effective investment decisions are not just about selecting the right fund; they also require strong financial planning and fiscal discipline. Professional tax advice helps investors optimize after-tax returns while remaining compliant with changing tax regulations. Why You Need a Chartered Accountant in Kerala to Navigate an Interval NFO Choosing an investment product is only one part of successful wealth management. Understanding its tax implications, monitoring portfolio performance, and aligning investments with your financial goals require professional expertise. Working with a chartered accountant in Kerala can help you: Analyze the tax and financial implications of an Interval NFO on your portfolio.Structure investments for better tax efficiency.Track portfolio performance over time.Plan capital gains strategically.Maintain complete tax compliance. At Team Taxperts, our experienced professionals provide personalized financial advisory, tax planning, compliance support, and investment-related guidance to help individuals and businesses make informed financial decisions with confidence. Who Should Ultimately Invest in an Interval NFO? An Interval NFO is not a one-size-fits-all investment and may not be suitable for every investor. It is generally best suited for institutional investors, corporate treasury departments, and retail investors whose