Stock Market Terminology
Stock market terminology – Explained When you step into the stock market, it is very important to understand the terms related to it. For a beginner, these terms may seem confusing at first, but over time, you will understand that they are an essential part of the stock market and its functioning. Knowing the basic stock market terminology is more than just gaining knowledge; it helps investors understand financial news, interpret stock quotes, and communicate. In this blog, Team Taxperts, a financial advisor in Kerala, explains some of the most commonly used stock market terms clearly and comprehensively. Having a basic understanding of these terms and gaining advanced knowledge can bring you one step closer to understanding the investment and stock market industry with greater confidence. Stock market terminology The stock market is a marketplace where stocks are bought and sold through organised exchanges, over-the-counter markets, and electronic trading venues. For beginners, learning the terminology used in this market is an important first step. The following terms cover some of the fundamental concepts investors encounter while reading stock market information. Basic Market Terms Share A share represents an ownership interest in a company. When you own shares of a company, you hold an equity interest in that business. Depending on the type of stock, shareholders may also have rights such as voting on certain corporate matters and receiving dividends when declared. Bull Market A bull market describes a period in which stock prices are generally rising, and investor sentiment is optimistic. A commonly used definition considers a broad market index to be in a bull market after it rises by 20% or more from a recent low. Bear Market A bear market refers to a period of declining stock prices accompanied by generally pessimistic market sentiment. A widely used definition describes a bear market as a decline of 20% or more in a broad market index from a recent high. Dividend A dividend is a distribution made by a company to its shareholders, generally from its profits. Companies that pay dividends may distribute them according to a regular schedule, while additional unscheduled payments can be declared as special dividends. Portfolio A portfolio is the collection of investments owned by an individual or institution. It can contain different types of assets, including stocks, bonds, commodities, real estate, and other investments. Building a diversified portfolio can help spread investment exposure across different assets. Trading and Prices Bid The bid is the highest price that a buyer is currently willing to pay for a specified number of shares. It represents the buying side of a stock quote. Ask The ask, also called the offer price, is the lowest price at which a seller is willing to sell a specified number of shares. The difference between the bid and ask prices is known as the bid-ask spread. Volume Volume refers to the number of shares traded during a specified period. Trading volume is commonly displayed alongside stock price information and can help investors understand the level of trading activity in a stock. Volatility Volatility refers to the degree to which the price of a stock or other financial asset fluctuates over time. A highly volatile stock can experience relatively large price movements within a short period, while lower volatility generally indicates smaller price fluctuations. Volatility is an important consideration because significant price movements can increase investment risk. IPO IPO stands for Initial Public Offering. It generally refers to the first time a company offers its shares to the public. An IPO allows a private company to become publicly traded, subject to the applicable regulatory and market requirements. Conclusion Understanding stock market terminology makes it easier to interpret market information and follow how stocks are traded. Terms such as share, bull market, bear market, dividend, portfolio, bid, ask, volume, volatility, and IPO describe fundamental aspects of investing and trading. However, knowing these terms is only the beginning. Investment decisions should also consider factors such as financial objectives, risk tolerance, diversification, company fundamentals, and applicable tax implications. For guidance on the tax aspects of investments and other financial matters, consulting Team Taxperts, a qualified tax consultant in Kochi, Kerala, can help you understand the relevant requirements and plan your finances more effectively.
Tax filing for business owners
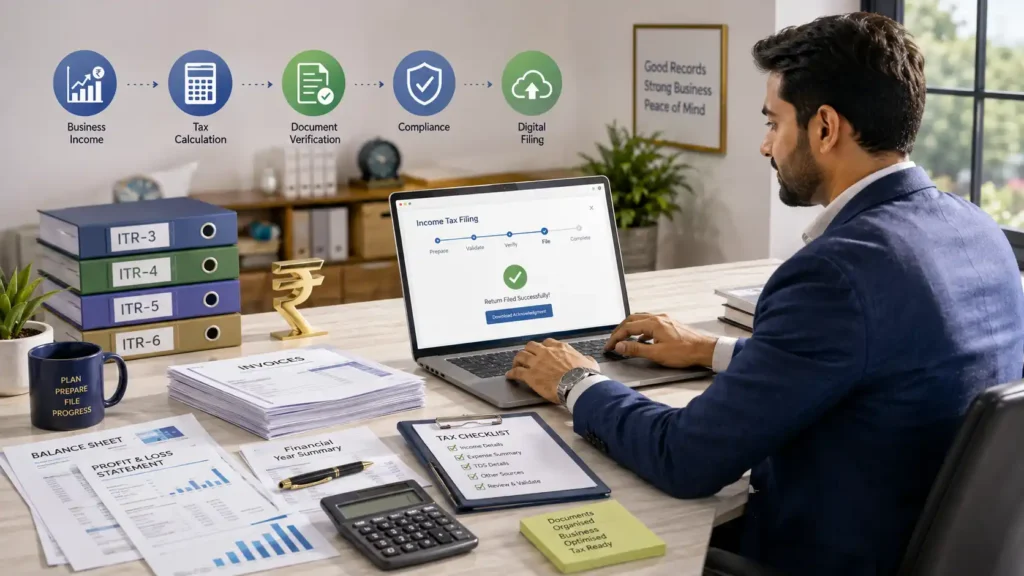
Managing a business involves several responsibilities, and keeping up with tax obligations is an important part of maintaining proper financial and regulatory compliance. For business owners, filing an income tax return requires attention to their business income, financial records, applicable tax provisions, and the ITR form relevant to their business structure. In this blog, Team Taxperts, a leading tax consultant in Kerala, explores tax filing for business owners, covering the essential ITR forms, the key documents required, and the basic steps involved in filing an income tax return. This guide will help business owners understand the requirements involved and prepare the necessary information and records for a smoother filing process. Tax filing for business owners-Explained For business owners, filing an income tax return means reporting the income earned from the business and providing the required financial and tax information to the Income Tax Department. The process may vary depending on whether the business is run as a proprietorship, partnership, LLP, company, or another type of entity. Knowing which ITR form to use, what documents to keep ready, and how to complete the filing correctly can help business owners avoid errors and meet their tax obligations on time. Essential ITR Forms for Business Owners The Income Tax Department provides different ITR forms for different categories of taxpayers. Business owners should select the form applicable to their legal status and income profile rather than choosing a form simply because they operate a business. For Assessment Year (AY) 2026–27, the principal forms relevant to many business structures include ITR-3, ITR-4 (Sugam), ITR-5, and ITR-6. ITR-3 ITR-3 applies to individuals and Hindu Undivided Families (HUFs) having income from profits and gains of business or profession. It can also cover taxpayers with income under other heads, such as salary or pension, house property, capital gains, and income from other sources, subject to the eligibility conditions for the form. This form is generally relevant when an individual or HUF has business or professional income that does not qualify for filing through ITR-4. ITR-4 (Sugam) ITR-4, also known as Sugam, is designed for eligible resident individuals, HUFs, and firms other than LLPs whose income from business or profession is computed under the presumptive taxation provisions of sections 44AD, 44ADA, or 44AE. For AY 2026–27, the applicable total-income limit specified by the Income Tax Department is ₹50 lakh, along with other eligibility conditions. Because ITR-4 is subject to specific eligibility requirements, taxpayers should confirm that their income sources and business circumstances satisfy those conditions before using the form. ITR-5 ITR-5 is used by specified entities other than individuals, HUFs, companies, and persons required to file ITR-7. This includes entities such as firms, Limited Liability Partnerships (LLPs), Association of Persons (AOPs), and certain other entities covered by the form. Therefore, the legal structure of a business is an important consideration when determining whether ITR-5 is applicable. ITR-6 ITR-6 applies to companies other than companies claiming exemption under section 11. Companies filing this return generally need to provide detailed information relating to their income, financial statements, and applicable tax provisions. Since company taxation can involve additional reporting and compliance requirements, companies should ensure that their books, financial statements, tax calculations, and other required information are properly reconciled before filing. Key Documents Required The exact documents and information required can vary depending on the business structure, nature of income, applicable tax provisions, and filing requirements. Maintaining the following categories of records can help business owners prepare an accurate return. Financial statements Business owners should keep their financial records organised, including the Profit and Loss Account, Balance Sheet, trial balance, and relevant books of account or accounting records. Supporting information for income, expenses, assets, liabilities, and other financial transactions should also be retained where applicable. These records help establish the figures reported in the ITR and provide a basis for reconciling the return with the business’s accounts. Tax tracking records Tax-related records should be maintained systematically. Depending on the business, these may include details of advance tax payments, self-assessment tax, Tax Deducted at Source (TDS), Tax Collected at Source (TCS), and other relevant tax information. Business owners should reconcile the tax information available in their records with the information reflected in the Income Tax Department’s records before submitting the return. Operational proofs Records supporting the actual operations of the business can be important for substantiating reported transactions. These may include sales invoices, purchase invoices, expense bills, bank statements, payment records, agreements, and other transaction-related documents relevant to the business. Maintaining these records in an organised manner can make it easier to verify income and expenses if clarification or supporting evidence is required later. Compliance documents Business owners should also maintain documents relating to applicable statutory and regulatory compliance. Depending on the nature and structure of the business, these may include registration details, GST-related records, audit reports, tax audit information where applicable, and other prescribed documents. Not every business will require the same set of documents. The applicable requirements should be determined based on the business structure and relevant provisions for the assessment year. Basic Steps to File The process of filing an income tax return for a business generally involves several stages: Identify the applicable ITR form: Determine whether ITR-3, ITR-4 (Sugam), ITR-5, ITR-6, or another form applies based on the taxpayer’s legal status, income, and applicable provisions. The Income Tax Department’s current guidance should be checked for the relevant assessment year. Organise financial records: Compile the financial statements, accounting records, invoices, bank information, tax records, and other supporting documents relevant to the return. Reconcile income and tax information: Cross-check business income, expenses, deductions, TDS/TCS information, advance tax, and other relevant figures before entering them into the return. Calculate taxable income and tax liability: Determine the taxable income after considering the applicable provisions, deductions, exemptions, and tax payments, as relevant to the taxpayer. Complete the ITR: Enter the required information accurately in the applicable ITR form. Business-related schedules and disclosures should be completed wherever applicable. Review before submission: Check the return
What are futures and options in the stock market
What are futures and options in the stock market Futures and options are important instruments in the derivatives segment of the stock market. Unlike directly buying or selling shares, these instruments involve contracts whose value is linked to an underlying asset. Understanding their rights, obligations, pricing, expiry, and risks is important before entering into a derivatives trade. SEBI also advises investors to understand the features and risk characteristics of derivatives before trading in them. With the expertise of Team Taxperts, a trusted financial advisor in Kerala, this blog explains the fundamentals of futures and options, how they work, and the key differences between these two derivative instruments. Understanding these concepts can help investors gain a clearer understanding of how futures and options function in the stock market and the risks associated with them. What is a Futures Contract? A futures contract is a standardised derivative contract through which two parties agree to buy or sell an underlying asset at a predetermined price on a specified future date, subject to the terms and settlement mechanism of the contract. The underlying asset may be a security, index, or another eligible asset, depending on the futures contract traded on the exchange. Obligation A key feature of a futures contract is that it creates an obligation for both the buyer and the seller. The buyer takes a long position, while the seller takes a short position, and both parties are bound by the contract according to its terms. Unlike an option buyer, a futures participant does not pay a premium to obtain a right. Instead, futures positions are subject to applicable margin requirements and clearing and settlement procedures. How does a Futures Contract work? When a trader enters a futures contract, details such as the underlying asset, contract price, quantity or lot size, and expiry are specified. The position is subject to mark-to-market settlement, under which gains and losses are calculated based on the applicable daily settlement price. For example, if a trader takes a long futures position at ₹1,000 per unit and the relevant settlement price rises to ₹1,050, the price difference is ₹50 per unit in favour of the long position. If the settlement price falls to ₹950, the difference is ₹50 per unit against the long position. The actual profit or loss depends on the contract’s lot size, settlement prices, transaction costs, and other applicable contract specifications. What is an Options Contract? An options contract is a derivative contract that gives the buyer the right, but not the obligation, to buy or sell an underlying asset at a predetermined strike price, subject to the terms and settlement mechanism of the contract. A Call Option gives the buyer the right to buy the underlying asset, while a Put Option gives the buyer the right to sell the underlying asset. Right The buyer of an options contract receives a contractual right to buy or sell the underlying asset at the specified strike price, depending on whether it is a Call Option or a Put Option. This right allows the buyer to benefit from favourable price movements without being required to exercise the option simply because it was purchased. Not an Obligation The option buyer is not obligated to exercise the option. The buyer can choose whether to exercise the right according to the terms of the contract. In contrast, the option seller, also known as the writer, assumes the corresponding obligation under the contract if the option is exercised or otherwise settled according to the applicable terms. Premium The buyer pays an amount known as the premium to acquire the option. The premium is influenced by factors such as the underlying asset’s price, strike price, time remaining until expiry, volatility, interest rates, and prevailing market conditions. For an outright option purchase, the buyer’s maximum loss on the option position is generally limited to the premium paid, along with applicable transaction costs. Types of Options There are two basic types of options: Call Options and Put Options. Call Option A Call Option gives the buyer the right, but not the obligation, to buy the underlying asset at the specified strike price, subject to the terms and settlement mechanism of the contract. A trader may buy a Call Option when expecting the price of the underlying asset to increase. If the underlying asset moves sufficiently in the expected direction, the Call Option may gain value. If the expected price movement does not occur to a sufficient extent, the option may expire without value, resulting in a loss of the premium paid by the buyer. For example, if a trader purchases a Call Option with a strike price of ₹1,000 and the underlying asset rises significantly above that level before expiry, the option may become more valuable. However, the movement in the underlying asset must be considered along with the premium paid, expiry, and other factors affecting the option’s price. Put Option A Put Option gives the buyer the right, but not the obligation, to sell the underlying asset at the specified strike price, subject to the terms and settlement mechanism of the contract. A trader may buy a Put Option when expecting the price of the underlying asset to decline. If the underlying asset falls sufficiently, the Put Option may increase in value. If the expected decline does not occur or is insufficient, the option may expire without value, and the buyer may lose the premium paid. Put Options can also form part of hedging strategies. For example, an investor holding an asset may use a Put Option to manage the potential downside associated with a fall in the asset’s price. Key Differences The main difference between futures and options lies in the obligations and risk involved. A futures contract creates an obligation for both the buyer and seller, whereas an options contract gives the buyer a right without an obligation to exercise it. Futures positions are subject to margin requirements, while an option buyer pays a premium to obtain the right. As a result,
Freelancer tax on foreign income in India
Do Freelancers Need to Pay Tax in India on US Dollar Earnings from Abroad? The rise of remote work and global freelancing has made it easier than ever for professionals in India to work with clients in the United States and other countries. As a result, many freelancers receive payments in US dollars or other foreign currencies directly into their Indian bank accounts. This often raises an important question: Do freelancers need to pay tax in India on income earned from foreign clients? In most cases, the answer is yes. However, the exact tax treatment depends on factors such as your residential status, the nature of your freelance services, the expenses you incur, and whether any tax has already been paid or deducted in the foreign country. This is why understanding freelancer tax on foreign income in India is important before filing your return. For freelancers earning from international clients, understanding both income-tax and GST rules is essential. A professional tax consultant in Kerala can help ensure that foreign income is reported correctly and that eligible deductions, tax credits, and GST benefits are properly claimed. In this blog, Team Taxperts explains the key tax and GST considerations that Indian freelancers should know when earning in US dollars or other foreign currencies from clients abroad. Understanding Taxability and GST on Foreign Remittances Receiving money in US dollars does not, by itself, make the income tax-free in India. The first step is to determine your residential status for Indian income-tax purposes. For tax years beginning on or after 1 April 2026, residential status is determined under the Income-tax Act, 2025. Generally, an individual who qualifies as a resident of India may be taxable in India on income within the scope of Indian tax law, including relevant foreign income. Non-residents are generally taxed in India on income that is received, accrues, or arises in India, subject to the applicable provisions. Therefore, a freelancer living and working in India cannot assume that payments received from a US client are outside the Indian tax net merely because the client is located abroad or the payment is made in US dollars. Income Tax on Foreign Freelance Income For an Indian freelancer, income earned from providing professional or freelance services is generally taxable under the head “Profits and gains of business or profession”, subject to the applicable provisions. The specific tax treatment may depend on the nature of the activity and the taxpayer’s circumstances. The amount received in foreign currency must be appropriately accounted for in Indian rupees for tax purposes. The freelancer should maintain proper records of invoices, payment receipts, bank statements, contracts, and other supporting documents. It is also important to distinguish between foreign currency receipt and foreign income. The fact that money is converted from US dollars to Indian rupees does not create a separate category of income. The underlying freelance earnings are what need to be considered for income-tax purposes. GST on Export of Services Freelancers providing services to clients located outside India may qualify as exporters of services under the GST law if the prescribed conditions are satisfied. Broadly, these conditions include the supplier being located in India, the recipient being located outside India, the place of supply being outside India, the consideration being received in convertible foreign exchange or as otherwise permitted under the applicable rules, and the supplier and recipient not being merely establishments of the same distinct person. Exports of services are zero-rated supplies under GST. An eligible registered exporter can generally supply services under a Letter of Undertaking (LUT) without payment of IGST, subject to the applicable requirements, or choose the route of paying IGST and subsequently claiming a refund, where permitted. However, not every payment received from a foreign customer automatically qualifies as an export of services. The nature of the service, location of the recipient, place-of-supply rules, and other statutory conditions must be examined. FIRC and Proof of Foreign Remittance Freelancers should maintain proper documentary evidence of payments received from overseas clients. Depending on the transaction and banking arrangement, documents such as a Foreign Inward Remittance Certificate (FIRC), e-FIRC, bank advice, bank statement, or other appropriate remittance documentation may help establish and substantiate the receipt and support GST and tax compliance. For GST purposes, proof of realisation of export proceeds can also become relevant in situations such as refund claims. CBIC has specifically referred to BRC/FIRC details in the context of export-of-services refund documentation. Therefore, freelancers should keep their invoices and corresponding bank/remittance records properly matched and preserved. How to Calculate Taxable Income and Save Legally Freelancers earning income from overseas clients can use certain provisions under Indian tax law to determine their taxable income and manage their tax liability legally. The key areas to consider include the treatment of genuine professional expenses, the applicable presumptive taxation scheme, and the possibility of claiming credit for taxes paid abroad. Deductible Business and Professional Expenses A freelancer who computes income based on actual profits may generally claim eligible expenses incurred wholly and exclusively for the purposes of the business or profession, subject to the applicable provisions. Depending on the nature of the freelance activity, examples may include: Laptop and other work-related equipment, subject to applicable depreciation rules Professional software and online subscriptions Internet and communication expenses Professional or co-working space expenses Advertising and marketing costs Professional consultancy and accounting fees Bank and payment-processing charges Other genuine expenses directly connected with the freelance business or profession Proper documentation is essential. Freelancers should retain invoices, bills, contracts, payment records, and other evidence supporting their claims. Personal expenses should not be presented as business expenses merely to reduce taxable income. Presumptive Taxation – Section 44ADA and the New Section 58 Many freelancers and independent professionals are familiar with Section 44ADA of the Income-tax Act, 1961, which provided a presumptive taxation scheme for specified professionals. However, there is an important update for 2026. The Income-tax Act, 2025 came into force from 1 April 2026, replacing the Income-tax Act, 1961 for tax
Can I file ITR without CA
Can You File Your ITR Without a CA? A Step-by-Step Guide for Taxpayers Filing an Income Tax Return (ITR) is an important annual responsibility for every eligible taxpayer in India. With the Income Tax Department’s online filing system becoming more user-friendly, many individuals now wonder: “Can I file ITR without a CA?” The answer is yes—many taxpayers can successfully file their ITR on their own if their income sources are simple and they understand the basic filing requirements. However, when tax situations become more complex, professional guidance can help avoid errors, missed deductions, and compliance issues. In this blog, Team Taxperts, a trusted Chartered Accountant in Kerala, explains when you can file your ITR independently and when professional assistance may be required. This blog also provides valuable insights to help you make informed decisions about your tax filing. When Can You File ITR Without a CA? You do not always need a Chartered Accountant to file your Income Tax Return. Individuals with straightforward financial situations can usually complete the process themselves through the Income Tax Department’s e-filing portal. You may consider filing your ITR without a CA in the following situations: Salaried Individuals Salaried employees with income primarily from salary, along with standard deductions and employer-issued Form 16, can generally file their ITR independently. If your salary details, deductions, and tax deducted at source (TDS) are accurately reflected in Form 16, the filing process is usually straightforward. Basic Interest Income If you earn interest income from savings accounts, fixed deposits, or other basic investments, you can report this income when filing your return. Ensure that all interest income is included, even if tax has not been deducted at source (TDS). Single House Property Taxpayers who own a single residential house property and earn income only from that property may be able to file their ITR without professional assistance, especially when there are no complex home loan calculations or multiple property transactions involved. Simple Capital Gains Individuals with straightforward capital gains, such as profits from the sale of listed shares or mutual funds, may be able to file their returns independently if they have accurate transaction statements and understand the applicable tax rules. Total Income Limit While there is no prescribed income limit for filing an ITR without a CA, taxpayers with straightforward income and financial activities often find self-filing manageable. Regardless of your income level, ensure that all income is reported correctly and the appropriate ITR form is selected. When Should You Definitely Hire a CA? While self-filing works for many taxpayers, certain situations require professional expertise. Mistakes in these cases can lead to incorrect tax calculations, notices from the Income Tax Department, or missed compliance requirements. You should consider hiring a Chartered Accountant if you fall under any of these categories: Business or Professional Income Individuals earning income from a business or profession often need to maintain proper books of accounts, calculate taxable income accurately, claim eligible expenses, and comply with additional tax requirements. Professional guidance can help ensure accurate reporting. Complex Capital Gains Capital gains involving multiple investments, property sales, unlisted shares, inherited assets, or other complex transactions may require detailed calculations. A CA can help determine the correct tax treatment and applicable exemptions. Foreign Assets & Income If you own foreign assets, receive income from outside India, hold overseas investments, or maintain foreign financial accounts, tax reporting requirements become more detailed. Incorrect disclosure can lead to serious compliance issues. Scrutiny Notices If you receive a notice from the Income Tax Department regarding your return, professional assistance is highly recommended. A CA can help you understand the notice, prepare the required response, and, where applicable, represent you before the tax authorities. Step-by-Step Process to File ITR on Your Own If your financial situation is simple and you decide to file your ITR independently, follow these steps carefully. Step 1: Gather Your Financial Documents Before starting the filing process, collect all the necessary documents, including: PAN and Aadhaar Form 16 from your employer (if applicable) Bank statements Interest certificates Investment proofs Capital gains statements (if applicable) Details of eligible deductions and exemptions Having complete information helps prevent mistakes during filing. Step 2: Cross-Verify with AIS and Form 26AS The Annual Information Statement (AIS) and Form 26AS, available on the Income Tax Department’s e-filing portal, provide details of financial transactions reported to the department. Review these documents carefully to verify: Salary income Interest income TDS details Investment-related transactions Other reported financial information If any information is incorrect or missing, take the necessary steps to update or reconcile it before submitting your return. Step 3: Choose the Correct ITR Form Selecting the correct ITR form is one of the most important steps in filing your return. The appropriate form depends on factors such as: Nature of income Residential status Business or professional income Capital gains Eligibility criteria prescribed for each ITR form Using the wrong ITR form may result in your return being treated as defective. Step 4: Review Pre-Filled Data and Submit The Income Tax Department provides pre-filled information in the online filing system based on available records. Before submission: Verify all pre-filled details Check income figures Confirm deductions claimed Review tax calculations Make corrections wherever required Once you are satisfied that all the details are accurate, submit your return online. Step 5: E-Verify Your Return (Crucial Step!) Filing your ITR is not complete until you verify it. You can complete e-verification through methods such as: Aadhaar OTP Net banking Bank account EVC Demat account EVC If you fail to verify your return within the prescribed time limit, your ITR will be treated as invalid. Top 3 Common Mistakes to Avoid Even simple ITR filings can contain errors. Avoid these common mistakes to ensure smooth processing of your return. Ignoring Interest Income Many taxpayers report only their salary income and forget to include interest earned from savings accounts, fixed deposits, or other sources. All taxable interest income must be disclosed while filing your return. Opting for the Wrong Tax