What is the Difference Between Bookkeeping and Accounting
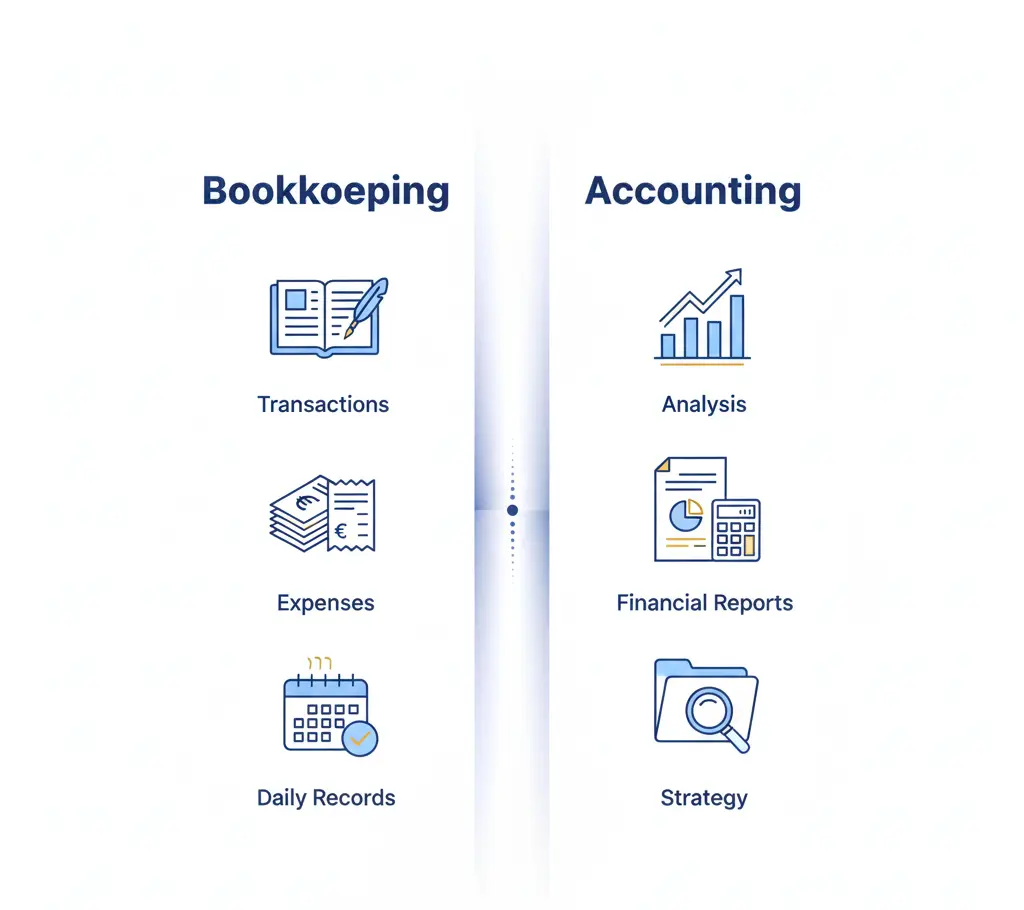
Understanding your company’s finances begins with two fundamental pillars: bookkeeping and accounting. Although these terms are frequently used interchangeably, they serve quite different purposes in keeping a corporation financially healthy. While accounting reads, analyzes, and turns that data into insightful information, bookkeeping concentrates on accurately recording daily transactions. In this blog, we’ll look at the major distinctions between bookkeeping and accounting, why they’re important, and how they operate together to enable wise decision-making and long-term growth. Whether you’re a small business owner or just entering into the world of finance, this guide will give you a clear and simple understanding of the two. At Team Taxperts, we simplify these processes for businesses by providing dependable accounting and bookkeeping services in India, assuring accuracy, compliance, and clarity at every stage. What is Bookkeeping Bookkeeping is the process of recording, organizing, and upholding all the financial transactions of a business daily. It entails tracking every sale, purchase, payment, invoice, and expense to verify that the company’s financial records are correct and up to date. Bookkeeping typically includes tasks like: Recording transactions in ledgers or software Managing invoices and receipts Tracking expenses and payments Reconciling bank statements Maintaining financial documents What is Accounting? Accounting is the process of interpreting, analyzing, and summarizing a company’s financial data to help make better decisions. While bookkeeping is concerned with recording financial data, accounting transforms that information into relevant reports. Accounting typically includes tasks such as: Preparing financial statements (like balance sheets, income statements, and cash flow statements) Analyzing profits, losses, and financial trends Budgeting and forecasting Ensuring tax compliance Helping with strategic planning and business growth Difference Between Bookkeeping and Accounting Although bookkeeping and accounting are closely related, they perform distinct functions in managing a company’s finances. Purpose Bookkeeping: Focuses on recording daily financial transactions. Accounting: Focuses on interpreting and analyzing those recorded transactions. Scope of Work Bookkeeping: Involves tasks like maintaining ledgers, tracking expenses, issuing invoices, and reconciling accounts. Accounting: Includes preparing financial statements, budgeting, tax planning, auditing, and offering financial insights. Objective Bookkeeping: Ensures accurate and organized financial data. Accounting: Uses that data to assess financial health and guide business decisions. Skills Required Bookkeeping: More transactional and administrative — requires attention to detail. Accounting: Requires analytical thinking, financial expertise, and knowledge of tax laws and reporting standards. Output Bookkeeping: Produces raw financial records. Accounting: Produces meaningful reports, insights, and strategies. Final Thoughts Bookkeeping and accounting may serve distinct tasks, yet together they constitute the foundation of any company’s financial health. While bookkeeping guarantees reliable, structured records, accounting turns those records into helpful insights that guide smarter decisions, strategic planning, and profitable development. Having the proper experts on your side is crucial for companies trying to maintain compliance and simplify their finances. That is why many businesses prefer to hire financial advisor India professionals that can manage both bookkeeping and accounting tasks with knowledge and precision. With the correct assistance, managing your financial health becomes easier, more obvious, and strategic. Reach out to Taxperts to streamline your bookkeeping and accounting needs.
Documents Required for New GST Registration in Kerala
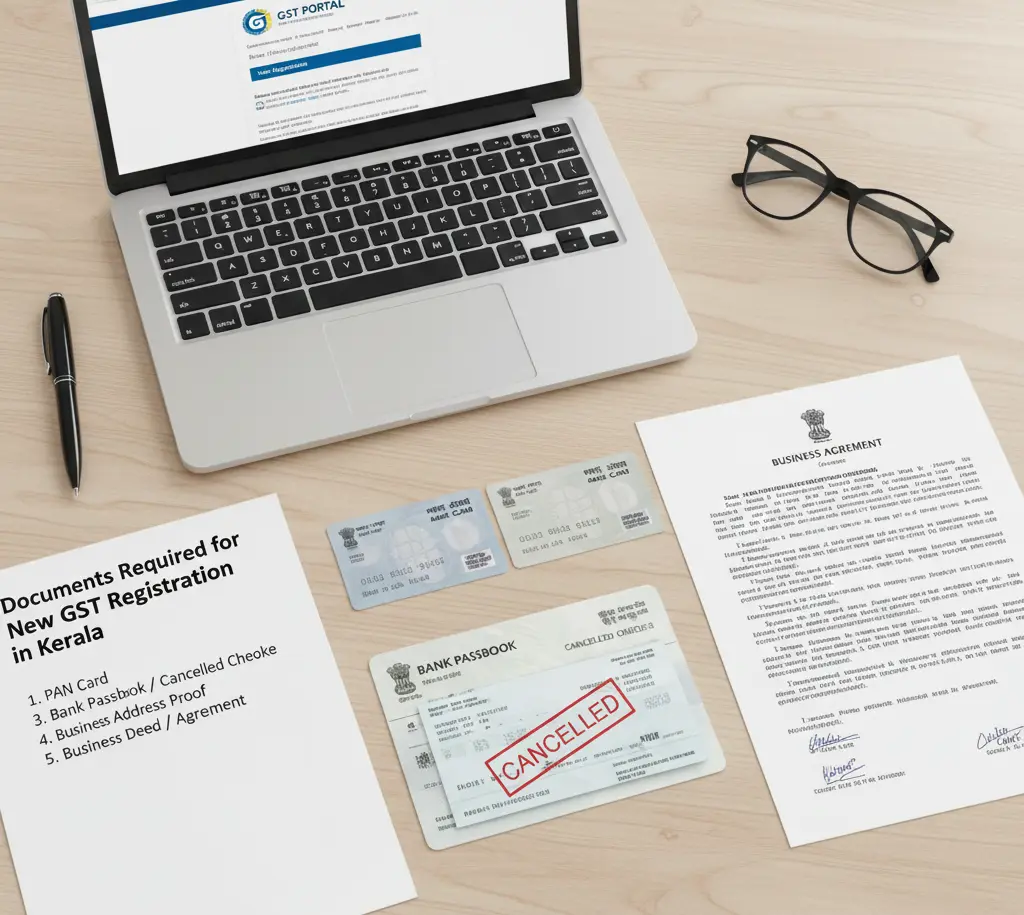
Starting a new business in Kerala? One of the first and most critical procedures is to complete your GST registration properly. Whether you’re a new entrepreneur, a small business owner, or expanding an existing venture, GST registration is required whenever you reach the prescribed revenue threshold. However, before you start the online process, having the necessary paperwork ready can save you time, prevent rejections, and ensure an effortless approval. In this blog, we’ll cover the primary documents required for new GST registration in Kerala, explain their importance, and guide how to upload them correctly. Let’s get you GST-ready the effortless way. These are the Documents Required for New GST Registration in Kerala To ensure a seamless and effective GST registration procedure in Kerala, businesses must provide appropriate documents verifying their name, business location, and financial information. Every document is essential to proving the applicant’s legitimacy and avoiding inconsistencies during verification. Here’s a detailed explanation of what you require and why: PAN: The Permanent Account Number (PAN) is a mandatory identifying document for GST registration. For individuals, the personal PAN is required, while for businesses such as partnerships, companies, or LLPs, the PAN of the organization must be submitted. It serves as the key tax identifier and connects all financial transactions into a single system. Identity and Address Proof with Photograph: Candidates must provide proof of identification and address, such as a driver’s license, passport, voter ID, or Aadhaar. These documents authenticate the applicant’s legitimacy and ensure that the GST registration is granted to a verified individual. A clean, current photograph is also necessary for supplementary identity verification. Proof of Business Address: To prove the physical address of your company, you must supply paperwork such as a rental agreement, utility bill, property tax receipt, or ownership document. This aids GST authorities in making sure that business operations are carried out at a legitimate and traceable address. Bank Account Details: Bank account information is required for integrating your business transactions into the GST system. A cancelled cheque, a copy of your passbook, or a bank statement can be submitted. These records aid in verifying the financial account linked to your company for compliance, payments, and refunds. Authorization Letter / Board Resolution: If your GST application is being filed by an authorized signatory rather than the business owner, you must provide a permission letter or board resolution. This document certifies that the person managing the GST processes is authorized to act on the company’s or entity’s behalf. Additional Documents Based on Business Structure Apart from the basic documents required for GST registration, Kerala businesses must also provide documentation unique to their business structure. These extra records assist authorities in confirming the entity’s ownership, legal establishment, and operational authorization. Sole Proprietorship: Sole proprietors must produce documents establishing their identity and ownership of the business. Typical supplementary documents consist of: Owner’s Aadhaar Card Owner’s PAN (mandatory as business PAN is not applicable) Trade license / Shop & Establishment Certificate These documents guarantee the legal recognition of the business and its owner as the same. Partnership Firm Documents attesting to the partnership’s existence and partners’ rights must be provided by partnership firms. Among them are: Partnership Deed PAN of the Partnership Firm Authorization letter from the partners Partner’s ID and address proof These documents affirm the legal structure and specify which partners are responsible for GST compliance. Limited Liability Partnership (LLP) Since LLPs are incorporated entities, their establishment must be validated by extralegal documents. These include: LLP Agreement Certificate of Incorporation issued by the Ministry of Corporate Affairs (MCA) Resolution appointing an authorized signatory Designated partners’ ID and address proof This guarantees that the firm complies with MCA standards and GST requirements. Private Limited Company Private limited corporations are required to submit thorough documentation proving their corporate identity and authorized representation. These include: Certificate of Incorporation issued by MCA Memorandum and Articles of Association (MOA & AOA) Board Resolution authorizing a director for GST activities Director’s ID and address proofs (DIN, PAN, Aadhaar, etc.) These records attest to the organization’s legal standing, governing body, and authorized staff. Final Thoughts The first step towards a fast and hassle-free GST registration in Kerala is to ensure that you have the necessary paperwork. From fundamental identity proofs to business structure-specific documentation, each criterion is critical to authenticating your firm and avoiding approval delays. Whether you’re a new entrepreneur or expanding your business, maintaining compliance from the start helps you develop a solid financial foundation. If you require expert guidance throughout the process, Taxperts can help you with professional support, precise documentation, and end-to-end compliance. For a smooth experience, always hire the best financial advisor in India—someone who genuinely understands the state’s regulatory system and ensures everything is done correctly. Are you prepared to have a stress-free GST journey? Let Taxperts take care of the details so you can concentrate on expanding your company.
Retirement Planning Tips for NRI
Introduction – NRI Retirement Planning for retirement is an essential step for everyone, but for Keralites, particularly for NRIs who are thinking of coming back home after years abroad, it possesses an even greater significance. The shift from an active profession abroad to a calm existence in India necessitates more than just savings; it also necessitates clarity, structure, and timely financial decisions. Proper tax planning and a well-thought-out investment strategy are critical in guaranteeing financial stability, protecting your money, and allowing you to live a stress-free post-retirement life. For NRIs, retirement planning entails understanding cross-border tax restrictions, selecting the best investment opportunities in India, obtaining healthcare, and establishing a corpus large enough to withstand inflation and lifestyle expenses. With the correct retirement planning tips for NRIs, you may make your return to Kerala easier, more financially secure, and really rewarding. Why NRIs and Kerala Residents Need Retirement Planning Retirement planning is vital for everyone, but NRIs and Kerala residents have distinct financial concerns. Many NRIs make money in foreign currencies that fluctuate, and their earnings frequently change based on the state of the world economy. This makes long-term financial stability more difficult to forecast unless accompanied by a robust, well-planned savings and investment strategy. A comfortable salary earned overseas might not be worth the same amount when translated into Indian rupees years later due to currency exchange rates. Family responsibilities offer a new level of difficulty. Keralites have traditionally supported old parents, educated children, and, on occasion, provided for extended family members, emphasizing the need of having a good financial strategy. Long-term settlement decisions for NRIs returning to Kerala, such as purchasing property, obtaining health insurance, or establishing a retirement fund, necessitate careful consideration and early planning. Furthermore, the rising cost of living and continually rising medical costs in Kerala make it even more necessary to plan. Healthcare, in particular, can become a considerable cost during retirement if not properly planned for. With appropriate planning, NRIs and Kerala natives can ensure their financial future, maintain their lifestyle, and retire in peace and security in their homeland. Factors to Consider Before Planning Retirement Before creating your retirement plan, consider a few critical elements that can impact your long-term financial security: Where You Plan to Settle (India or Abroad): Your retirement location influences your living expenditures, healthcare requirements, tax laws, and even the types of investments that will work best for you. Whether you choose to stay abroad or settle back in India, particularly in Kerala, your financial approach ought to comply with your future living environment. Expected Expenses After Retirement: Estimate your post-retirement expenses, such as housing, food, healthcare, travel, and leisure. Living costs in Kerala are rising gradually, especially for medical care, making accurate expense estimation essential for long-term comfort. Tax Implications of Foreign and Indian Income: NRIs must evaluate how their income, whether earned overseas, repatriated, or created through investments in India, will be taxed. Understanding double taxation rules, NRE/NRO account taxation, and residency status can help maximize returns and prevent excessive tax burdens. Investment Liquidity and Safety: A strong retirement portfolio strikes the right balance between growth and safety. Give top priority to assets that provide steady returns and simple liquidity in times of need. NRIs should also carefully assess risk levels to ensure that their retirement funds are protected against market fluctuations. Best Retirement Investment Options for NRIs Planning for a solid financial future is made easier when you select the correct balance of steady and growth-oriented assets. Here are some of the most trusted retirement investment alternatives for NRIs: NPS (National Pension System): NPS is a good long-term retirement option for NRIs with Indian bank accounts. It provides professional fund management, market-linked returns, and tax advantages. A portion can be taken out in one lump amount at retirement, while the remainder offers lifetime pension income. EPF (Employees’ Provident Fund) for Returning NRIs: NRIs who have previously worked in India and made contributions to the Employee Provident Fund (EPF) may continue to get benefits if they return. EPF serves as a reliable retirement safety net and offers secure, fixed-interest returns, particularly for individuals returning to the Indian job market. PPF (Public Provident Fund): PPF is a government-backed investment with a 15-year lock-in that offers long-term, tax-free earnings. Though NRIs are not permitted to register new PPF accounts, existing ones (opened prior to NRI status) can be maintained till maturity, making it a safe option for retirement savings. NRE/NRO Fixed Deposits: These fixed deposits are preferred among NRIs due to their stability. NRE FDs: Tax-free in India, fully repatriable, but interest rates may be lower. NRO FDs: Higher interest rates but taxable in India; useful for income earned within the country. Both options provide guaranteed returns and low risk. Mutual Funds / SIPs: Mutual funds and SIPs provide flexibility and long-term wealth growth for NRIs looking for greater returns. Equity, debt, and hybrid funds can be selected based on risk tolerance. Many AMCs allow NRIs to invest with the correct KYC and documents. Real Estate in Kerala: Purchasing property in Kerala provides two purposes: an appreciating investment and a future retirement home. Whether you’re building a house, buying a villa, or investing in a rental property, real estate can help you achieve both financial and lifestyle goals for your return. Tax Planning for NRI Retirement Tax planning is an essential aspect of NRI retirement planning, particularly for those wanting to return to India. Understanding how taxes apply to various sources of income ensures that your savings are protected and your post-retirement cash flow is consistent. How Indian Taxation Applies to NRIs Non-resident Indians are taxed exclusively on income generated or received within India. This comprises: Investment income: Returns from NRE/NRO fixed deposits, mutual funds, and other financial instruments. Pension income: Pensions received in India are taxable depending on the individual’s income slab. Rental income from property: Rent received from property in Kerala or elsewhere in India is taxable, though certain deductions (like a standard 30% deduction, municipal
How to Plan Retirement: Tips & Strategies for a Secure Future
Planning for retirement is more than just conserving money; it is also about shaping the life you want to live tomorrow. It’s the point at which your efforts finally pay off and you are free to decide how you want to spend your days. Your retirement can represent the lifestyle you’ve always envisioned, whether it’s tranquil mornings, exciting travels, or just a stress-free future. But making those ambitions a reality needs careful planning and sound financial decisions. The earlier you begin, the more control you will have over your future comfort and security. With the correct plan in place, your retirement years might be the most fulfilling period of your life. What is Retirement Planning Retirement planning is the process of arranging your finances, lifestyle, and long-term goals to live a comfortable, secure life after you retire. It entails figuring out how much money you’ll need, accumulating savings through investments and pension plans, and controlling spending so you can continue living the way you want. Retirement planning also entails assessing healthcare needs, putting up emergency funds, and determining how your income will be sustained through pensions, savings, or passive earnings. Beyond money, it’s about imagining what you want to do with your time, be it traveling, engaging in hobbies, or just relaxing. Types of Retirement Planning Financial Planning: This focuses on investing, saving, and accumulating wealth to sustain your way of life in retirement. It consists of pension plans, mutual funds, fixed deposits, retirement accounts, and other long-term savings investments. Investment Planning: This entails selecting the best investment options, such as stocks, bonds, real estate, or annuities, in order to grow your money over time and outperform inflation. Income Planning: This guarantees that you will have a consistent income in retirement through dividends, annuities, pensions, rental income, and methodical withdrawals. Expense Planning: Here, you plan for future living costs, like daily expenses, leisure activities, travel, and emergencies, to handle your retirement budget efficiently. Healthcare & Insurance Planning: This includes medical insurance, long-term care, emergency reserves, and other health-related costs that often rise with age. Tax Planning: Retirement tax planning helps you reduce taxes on withdrawals, pensions, investments, and savings, allowing you to keep more of your money. Estate & Legacy Planning: This involves determining how your assets (property, savings, and investments) will be managed or passed down to your family or beneficiaries. Lifestyle Planning: Beyond financial considerations, this focuses on your individual objectives, such as your ideal home, hobbies, and post-retirement lifestyle. Why is Retirement Planning Important? Retirement planning is essential because it provides financial security and peace of mind when your regular income ends. It enables you to sustain your way of life, pay for necessities, and relish your older years stress-free. With rising healthcare costs and inflation, having a sound plan might help you avoid unforeseen financial challenges. Additionally, it frees you from financial concerns so you can follow your ambitions, whether they involve travel, hobbies, or spending time with loved ones. Ultimately, retirement planning allows you to remain independent, confident, and ready for whatever the future holds. When Should One Start Planning for Retirement? It’s advised to start planning for retirement as early as possible, preferably in your 20s or as soon as you start earning. Starting early provides your money more time to compound, relieves financial stress later, and enables you to establish a stronger, more flexible retirement fund. However, it’s never too late to start. Even if you start in your 30s, 40s, or 50s, careful planning, disciplined saving, and the correct investments can lead to a secure and enjoyable retirement. How to Plan Retirement? Set Clear Retirement Goals: Choose your retirement date and lifestyle, whether it be simple living, travel, hobbies, or a combination of all of these. Estimate Future Expenses: Determine how much you’ll need for emergencies, travel, daily living, healthcare, and lifestyle activities once you retire. Start Saving Early: Begin investing in retirement funds, pension plans, or savings accounts as soon as you start earning. Over time, small amounts increase dramatically. Invest Wisely: Choose a combination of investments, like mutual funds, stocks, fixed deposits, or real estate, to expand your wealth and safeguard it from inflation. Build a Retirement Corpus: Establish a goal for how much you want to have by the time you retire, then monitor your progress on a regular basis. Secure Health Insurance: Having solid health insurance and emergency savings is crucial because medical expenses increase with age. Reduce Debt Before Retirement: Aim to pay off loans, credit card payments, and other debts before retiring to keep your savings intact. Create Multiple Income Streams: Plan for pensions, rental income, dividends, and part-time work to supplement your retirement income. Review & Adjust Regularly: Life changes, so review your strategy annually and alter your savings or investments as needed. Plan Your Legacy: Prepare your will, nominate beneficiaries, and prepare how your assets will be passed down. Why Retirement Planning is Important in India Retirement planning is especially important in India, where the traditional support system of relying on children or joint families is shifting. With growing living expenditures, increased life expectancy, and rising healthcare costs, having a large financial buffer has become critical. Most private-sector jobs do not provide pensions, so employees must generate their own retirement income. Inflation also slowly diminishes the value of savings, making planned investments a requirement rather than an option. Effective retirement planning helps you maintain a comfortable living even when your regular income quits, assures financial freedom, and keeps you from being dependent on others. Early planning is essential to ensuring a stress-free and respectable future in a world that is changing quickly. Tax-Saving Options for Retirement Planning Tax-saving strategies are critical in developing a robust retirement portfolio while lowering your annual tax burden. Popular choices such as NPS, PPF, EPF, ELSS, insurance plans, and annuities not only help you save consistently, but they also provide significant tax benefits under Sections 80C, 80CCD, and other laws. The
Marriage and Tax Benefits

Marriage is a significant life event that is full of joy, celebration, and fresh starts. However, marriage also entails several financial issues, particularly with regard to taxes, in addition to the planning of the wedding and honeymoon. From filing status to deductions, credits, and potential traps, understanding how marriage affects your tax situation is critical for creating a solid financial future together. In this blog, we’ll go over the essentials to assist couples in confidently navigating the often-confusing intersection of love and taxes. Marriage and Tax Benefits Beyond the emotional benefits, marriage can offer substantial financial benefits. Couples who file jointly may be eligible for bigger standard deductions, valuable tax credits, and more favorable tax brackets, thereby lowering their total tax burden. Marriage can affect retirement contributions, inheritance planning, and health-related tax benefits in addition to immediate savings. Knowing these benefits enables couples to maximize the benefits of being legally joined in marriage by making well-informed financial decisions. Tax Benefits During Marriage Wedding Gifts Are Tax-Exempt: Gifts received from immediate family members during your wedding are exempt from income tax under Section 56 of the Income Tax Act. You can cherish these thoughtful gifts without worrying about tax implications. Wedding Expenses Aren’t Taxable: Expenses incurred for your wedding are considered personal expenditures and are not taxable, allowing you to plan your celebration freely. Joint Filing Benefits: Married couples can file taxes jointly, often resulting in lower tax rates and access to higher deductions. Higher Standard Deduction: Couples filing jointly can claim a larger standard deduction, reducing taxable income and increasing potential savings. Access to Tax Credits: Marriage can make you eligible for credits like the Child Tax Credit, Earned Income Tax Credit (EITC), and education-related credits. Spousal IRA Contributions: Even if one spouse has no income, the other can contribute to a Spousal IRA, gaining additional tax-deferred retirement benefits. Estate and Gift Tax Benefits: Spouses can transfer assets to each other without triggering gift taxes, simplifying estate planning. Tax Benefits After Marriage Double Home Loan Deductions: If both partners are earning and jointly own a house with a joint home loan, each spouse can file for deductions individually. Under Section 80C, both can claim up to ₹1.5 lakh each on principal repayment, and under Section 24(b), up to ₹2 lakh each on interest. All of that could result in a ₹7 lakh deduction, which would drastically lower your taxable income. Higher Health Insurance Deduction: Both couples with health insurance coverage can claim tax benefits under Section 80D, up to ₹25,000 each or ₹50,000 combined. This guarantees both financial security and significant tax savings. Smarter Income Planning Between Spouses: If one spouse earns less or does not work at all, couples can maximize their investments by transferring funds or placing investments in the name of the lower-income spouse. This can help move some taxable income to a lower bracket, lowering the family’s overall tax burden. House Rent Allowance (HRA) Exemption: If both partners receive HRA as part of their pay and live in rented housing, they can claim an HRA exemption based on their individual salaries and rent contributions. As a result, the tax relief provided for housing expenses is essentially doubled. Enhanced Financial Planning Opportunities: Marriage enables couples to combine financial goals—such as home ownership, retirement, or insurance—and arrange investments in a way that optimizes deductions while minimizing taxes. Sources of Income for Unsalaried Housewives There are still ways to create money while staying at home. In today’s society, women can generate money from a variety of sources, both traditional and modern, while also managing their household obligations. Here are a few common income sources that can be stated when completing income tax returns: Rental Income: If a housewife owns rented property, the rent she receives becomes a reliable source of income. This income is taxable under the head ‘Income from House Property’ after permissible deductions. Dividend Earnings: Investments in mutual funds or corporate stock can produce dividend income, providing consistent profits without the need for active labor. It is necessary to record these incomes while filing taxes. Interest from Savings and Deposits: Interest earned on savings accounts, fixed deposits, recurring deposits, or other savings instruments is classified as ‘Income from Other Sources’ and is taxed over the applicable exemption levels. Capital Gains: Selling assets such as property, gold, or shares can result in capital gains, which are taxable depending on whether the asset was held for a short or long period of time. Home-Based or Freelance Work: Many homemakers earn money through small enterprises or freelance work, such as tutoring, catering, online craft sales, or digital services. Under “Profits and Gains from Business or Profession,” this income is subject to taxation. Gifts and Inheritances: Gifts from non-relatives that total more than ₹50,000 in a fiscal year are taxable, whereas gifts from relatives are tax-free. In a similar vein, inherited property is exempt, but any income derived from it may be subject to taxation. Pension or Family Pension: A housewife’s family pension is considered taxable income under ‘Income from Other Sources’, although some reductions are possible. Income Tax for Housewives in India Housewives are essential to household management, and many now earn income from investments, home-based jobs, or other sources. Housewives may still need to file an Income Tax Return (ITR) if their income exceeds the basic exemption limit, even if they do not have a permanent wage. In India, the standard exemption limit under the Income Tax Act for individual taxpayers (below 60 years) is ₹2.5 lakh per financial year. If a housewife’s total annual income, including rent, interest, capital gains, and freelance labor, exceeds this amount, she must submit an ITR. Tips to Save Income Tax – Married Couples Opt for Joint Home Loans: If both partners work, obtaining a joint home loan can increase your tax benefits. Partners can deduct up to ₹1.5 lakh under Section 80C for principle repayment and ₹2 lakh under Section 24(b) for interest payments. That’s a total of ₹7